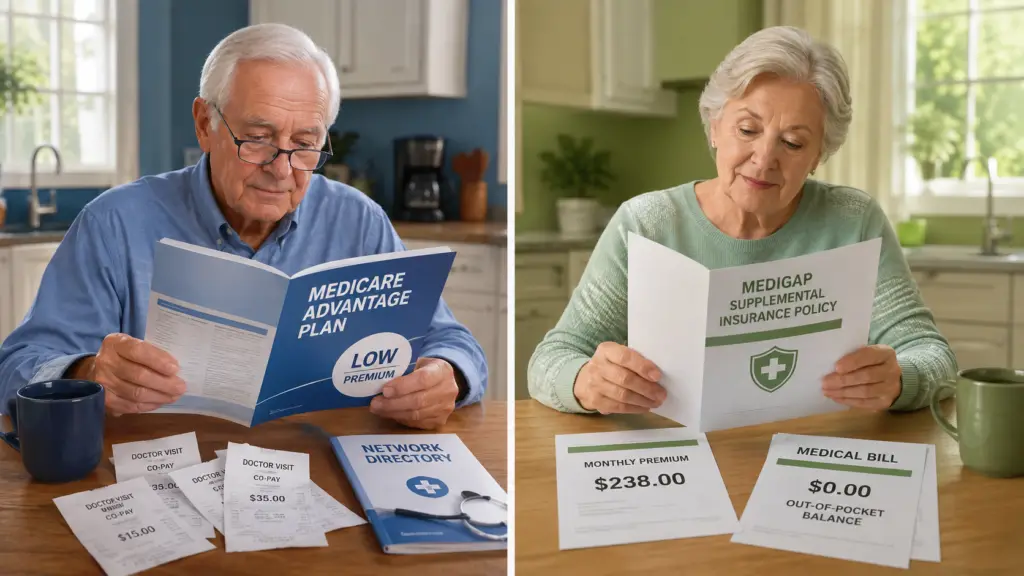
Choosing between Medicare Advantage vs Medigap costs is one of the most consequential financial decisions a retiree will ever make. And it’s one that most people get wrong because they’re focused on the wrong number. Monthly premiums feel simple and concrete. But the real story only shows up when someone actually needs care.
This guide cuts through the confusion with real 2026 numbers, so retirees can make an informed choice with confidence.
Medicare Advantage often has lower (or $0) monthly premiums but can expose retirees to thousands in out-of-pocket costs during a serious health event. Medigap, especially Plan G carries a higher monthly premium but delivers highly predictable costs year-round. The right choice depends on health status, budget, and how much financial uncertainty someone can comfortably absorb.
What’s Actually Being Compared Here
Before diving into dollars, it helps to understand what each path really involves.
Medigap, also called Medicare Supplement Insurance, is private insurance that works alongside Original Medicare, covering most or all of the cost-sharing that Medicare leaves behind deductibles, coinsurance, and copays.
Medicare Advantage works completely differently.
It’s different in kind, not just degree; instead of working alongside Original Medicare, Medicare Advantage replaces it entirely.
Think of it this way: Medigap is like adding a safety net under a trapeze. Medicare Advantage is like switching to a different trapeze altogether with its own rules, its own net, and its own boundaries on where you can swing.
The real cost picture changes dramatically based on how a person receives care, how often they travel, what doctors they use, which prescriptions they take, and whether they want predictable costs or lower monthly premiums with more cost-sharing later.
The Baseline: What Everyone Pays First
In 2026, the standard Medicare Part B premium is $202.90 per month and the Part B deductible is $283 and those amounts apply whether a person chooses Original Medicare with a Medigap policy or enrolls in a Medicare Advantage plan.
That’s the shared starting line. From there, the two paths diverge significantly.
The Part A inpatient hospital deductible sits at $1,736 per benefit period, with Part A daily coinsurance running $434 per day for days 61–90 of a hospital stay.
Without supplemental coverage of some kind, those numbers can add up fast.
Medicare Advantage Costs: The Monthly Savings and the Hidden Catch
The Premium Appeal
Most Medicare Advantage enrollees pay little or nothing beyond their Part B premium of $202.90 a month in 2026, and about three-quarters of people in individual Medicare Advantage plans with drug coverage pay no separate premium at all.
That’s a genuinely attractive starting point. Zero extra premium each month sounds like a great deal and for healthy retirees, it often is.
The Out-of-Pocket Maximum Medicare Advantage Carries
Here’s where the math gets more complex.
In 2026, the out-of-pocket limit for Medicare Advantage plans may not exceed $9,250 for in-network services and $13,900 for a combination of in-network and out-of-network services.
Those are the legal ceilings but that doesn’t mean every plan hits them.
The average enrollment-weighted out-of-pocket limit for Medicare Advantage enrollees is $5,421 for in-network services and $9,825 for in-network and out-of-network services combined.
So even the “average” scenario can leave a retiree facing more than $5,000 in a difficult health year.
Once that out-of-pocket limit is reached, the plan pays 100% of covered health services for the rest of the year; which is a real and meaningful protection.
Network Restrictions Medicare Advantage Imposes
Medicare Advantage plans often have a limited network of providers, which can restrict beneficiary choice of physicians and hospitals. More than half of Medicare Advantage beneficiaries are enrolled in HMO plans that typically do not cover out-of-network services.
The size of Medicare Advantage provider networks for physicians varies greatly across counties and across plans in the same county, with beneficiaries having access to about half of the physicians available to traditional Medicare beneficiaries in their area, on average.
And prior authorization remains a significant factor. Original Medicare enrollees rarely face prior authorizations; they’re far more common for people who have Medicare Advantage plans.
Even with 2026’s updated rules requiring faster decisions, it’s still an added layer between a patient and their care.
Medigap Plan G Premium 2026: What Predictability Costs
The Monthly Premium Reality
The most popular Medigap plan for new enrollees right now is Plan G.
Plan G averages $220 a month at age 65; though the actual range is broader.
Medicare Supplement Plan G premiums in 2026 typically range from about $140 to over $400 a month, depending on age, ZIP code, gender, tobacco use, household discounts, and the company chosen.
Geography matters enormously here.
In Texas in 2026, many shoppers see Plan G around $120 to $170 per month, while in New York, where community rating is required, Plan G averages around $354 a month.
What That Premium Actually Buys
The trade-off for that higher monthly cost is significant.
With Medigap Plan G, the only required out-of-pocket cost for covered services is the Part B annual deductible of $283 in 2026 after that, Plan G covers 100% of Medicare-approved charges.
After the deductible, Plan G covers virtually all Medicare-approved expenses with no surprise bills, no copays, and no network restrictions.
That last phrase is worth pausing on. No network restrictions means a retiree can see any doctor in the country who accepts Medicare, no referrals, no prior authorization for most services, and no worrying about whether a specialist is “in-network.”
How Medigap Premiums Can Grow Over Time
One important caveat: most Medigap plans use attained-age pricing, which means the premium climbs with each birthday on top of any general rate increase.
The average Medigap premium is $189 a month at age 65 and rises to $238 by age 75, nearly $600 more a year.
Comparing carriers regularly is well worth the effort.
Because Plan G benefits are standardized, comparing prices before enrolling or after having the plan a few years can often save thousands of dollars over time.
Side-by-Side: Where Each Plan Wins
Here’s how the two paths compare across the scenarios that matter most to retirees.
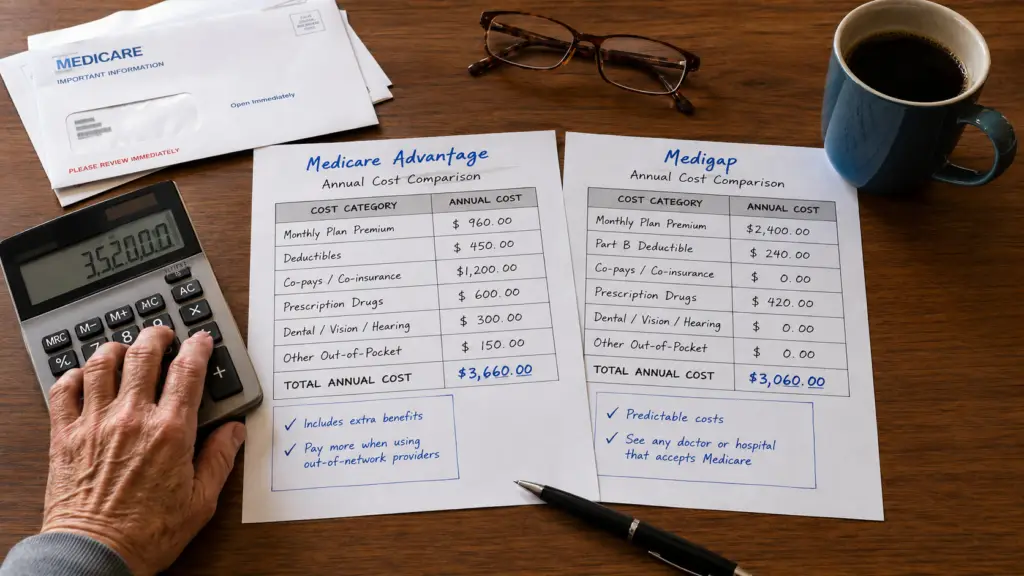
Healthy years with few medical needs: For healthy years, Medicare Advantage costs less. For years with significant medical needs, Medigap usually wins.
A $0-premium Medicare Advantage plan keeps more cash in a retiree’s pocket month to month when doctor visits are infrequent.
Serious illness or hospitalization: Medigap and Medicare Advantage handle medical bills in very different ways, and the real cost difference between the two only truly shows up once care is actually needed. Medicare Advantage usually costs less every month but has higher out-of-pocket costs, while Medigap charges a higher premium but leaves enrollees with little or nothing to pay when a hospital bill arrives.
Travel and provider flexibility: Medigap wins clearly here. Because it works with Original Medicare supplement coverage nationwide, retirees who split time between states or travel frequently don’t have to worry about network boundaries.
Prescription drug coverage: Neither plan includes it automatically. Medicare Advantage plans often bundle Part D coverage, while Medigap enrollees need a separate Part D plan.
Out-of-pocket limits for Medicare Advantage apply to Part A and B services only and do not apply to Part D spending, which has a separate out-of-pocket limit of $2,100 in 2026.
Which Path Is Right for You?
The central finding is simple: the true Medicare costs are not just premiums. It’s the combination of premiums, deductibles, copays, coinsurance, prescription costs, provider access, plan rules, and future flexibility that determines real value.
Retirees who are generally healthy, budget-conscious month to month, and comfortable with some network structure may find Medicare Advantage offers excellent value. But retirees managing chronic conditions, those who value freedom to choose any Medicare provider, or anyone who wants to eliminate financial unpredictability tend to find that Medigap, particularly Plan G delivers the peace of mind worth paying for.
One more timing note worth knowing: the Medigap Open Enrollment Period is a six-month window starting the month someone turns 65 and enrolls in Part B. During this window, carriers cannot deny coverage or charge more for pre-existing conditions after it ends, medical underwriting and higher rates may apply.
That window is one of the most valuable opportunities in all of Medicare planning.
Frequently Asked Questions
Can someone switch from Medicare Advantage to Medigap later?
It’s possible, but not always easy. Outside of the Medigap Open Enrollment Period, most states allow insurers to use medical underwriting, which means a pre-existing condition could lead to denial or higher premiums. Switching is cleanest when done during that initial enrollment window at 65.
Does Medicare Advantage really cover dental and vision that Medigap doesn’t?
Medicare Advantage plans often have lower monthly premiums and many include extra benefits
like dental, vision, and hearing which original Medicare supplement coverage doesn’t include. But it’s important to read the fine print, as these benefits vary widely by plan and county.
What if someone can’t afford Medigap premiums?
A High-Deductible Plan G is worth exploring.
High-deductible Plan G costs $61 a month but requires $2,950 out-of-pocket before coverage begins; offering a middle ground between the predictability of standard Plan G and the low premiums of Medicare Advantage.
Medicare Advantage vs Medigap costs isn’t a contest with one universal winner. It’s a deeply personal financial calculation one that depends on health, lifestyle, risk tolerance, and retirement budget. But the good news is that both paths offer real protections, and understanding the numbers makes the choice much clearer.
The smartest move any retiree can make is to work with a licensed, independent Medicare advisor who can compare actual plans and premiums in their specific ZIP code. Real numbers, real plans, real peace of mind, that’s the goal, and it’s absolutely achievable. Schedule a consultation with Aidan Neshite today.